Join our next workshop: Risk Transfer 101 coming up on Nov 18th

Guide

How to Read and Verify an ACORD 25 Certificate of Insurance

An ACORD 25, the Certificate of Liability Insurance, is the standard one-page form an insurance agent or broker issues to summarize a business's liability coverage. Here's how to read every field, what to check against your contract, and which red flags to escalate.

What is an ACORD 25?

An ACORD 25 is the industry-standard Certificate of Insurance (COI) that summarizes a company's liability coverage, policy limits and effective dates without requiring access to the full insurance policy. It's the most common document commercial brokers rely on to verify that vendors, contractors and partners carry the insurance required by contract. The current edition is ACORD 25 (2016/03).

Evident automates collecting COIs and checking them against your requirements. Even so, anyone who reviews certificates, in risk, compliance or procurement, should know how to read one by hand.

The 20 fields, explained

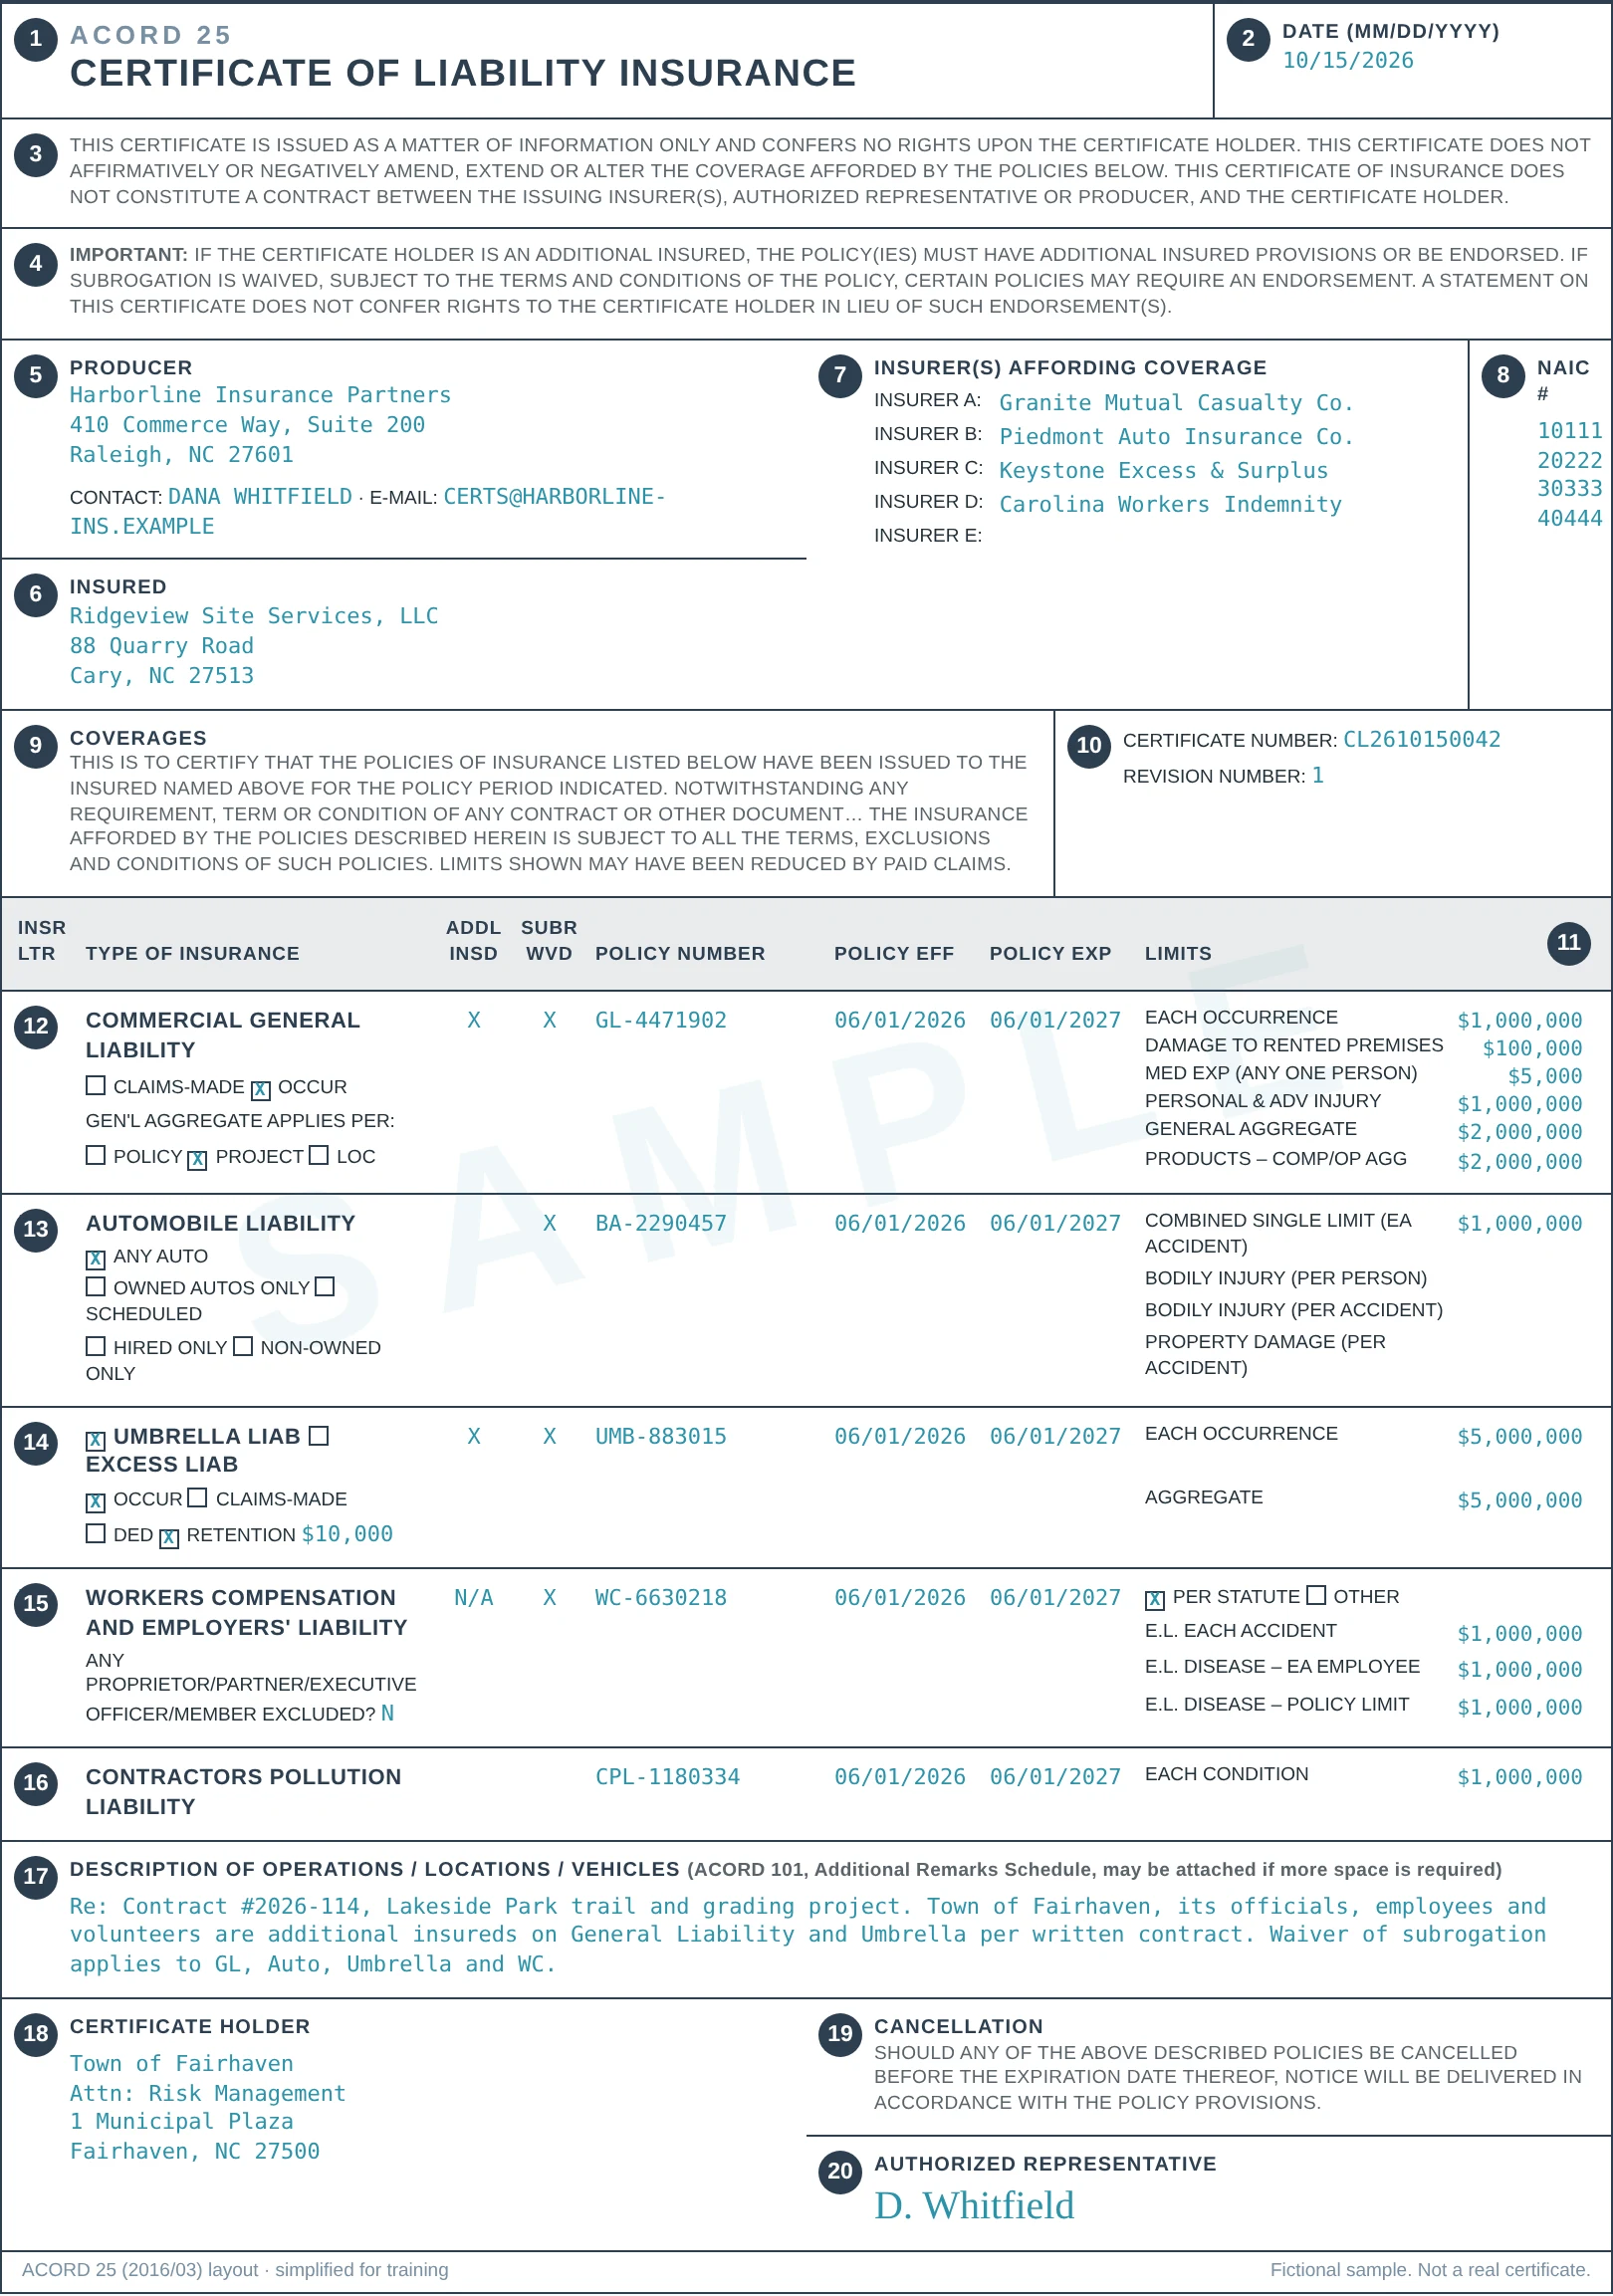
Sample ACORD 25 certificate of liability insurance with its 20 fields numbered, from the header and producer through coverages, certificate holder and signature (opens the full-size image in a new tab)
Fictional sample ACORD 25 with each field numbered. Not a real certificate. Click to enlarge.Fictional sample for training. Not a real certificate. ACORD is a registered mark of ACORD Corporation.

HeaderFields 1–4

1. Form title

Field on the form: CERTIFICATE OF LIABILITY INSURANCE

Identifies which ACORD form you received. The ACORD 25 is the standard certificate for liability coverage. Other ACORD forms cover different things: ACORD 23 for auto, ACORD 24 for property, and ACORD 27 and 28 as evidence of property insurance.

What to check

  • Confirm it's the form you asked for (usually ACORD 25 for vendors and contractors).
  • Older editions of the form are generally acceptable; brokers don't always use the newest version.

On the sample:An ACORD 25 liability certificate, which is what a contractor agreement normally calls for.

2. Issue date

Field on the form: DATE (MM/DD/YYYY)

The date the producer issued this certificate. It says nothing about when coverage starts or ends; those dates are in the coverage section.

What to check

  • The date should be recent, ideally issued for this specific contract or event.
  • Compare it with the policy dates below. A certificate issued before the policy period is a reason to ask questions.

Red flag:A missing or months-old date can signal a recycled or altered certificate.

On the sample:Issued 10/15/2026, during the 06/01/2026 – 06/01/2027 policy term.

3. Information-only disclaimer

Field on the form: THIS CERTIFICATE IS ISSUED AS A MATTER OF INFORMATION ONLY…

This legal notice says the certificate only reports that insurance was purchased. It gives the certificate holder no rights under the policies, and it cannot change the coverage in any way. Whatever the policies say is what applies.

What to check

  • Don't treat the certificate as proof that you're protected. Being listed as certificate holder doesn't make you an insured.
  • Use your contract to require the protections you need, then verify them with endorsements.

On the sample:Standard current ACORD wording. You can't negotiate this text; it appears on every ACORD 25.

4. Additional insured and subrogation notice

Field on the form: IMPORTANT: IF THE CERTIFICATE HOLDER IS AN ADDITIONAL INSURED…

A warning that additional insured status and waivers of subrogation only exist if the policy itself provides them, usually by endorsement. A checkmark or note on the certificate is not a substitute.

What to check

  • Check your contract: does it require additional insured status, a waiver of subrogation, or both?
  • If so, ask the producer for copies of the endorsements, not just the certificate.
  • Additional insured: the insurer will defend and pay for claims against you arising from the insured's work.
  • Waiver of subrogation: after paying a loss, the insurer gives up its right to recover that money from you.

PartiesFields 5–8

5. Producer

Field on the form: PRODUCER · CONTACT · PHONE · E-MAIL

The insurance agent or broker who placed the coverage. The producer issues the certificate on the insurers' behalf and is the right person to call with questions about it.

What to check

  • Some risk managers strongly prefer, or require, that certificates come straight from the broker. Others accept them from the vendor for practical reasons. Either can work, but for a new vendor or a large or high-risk contract, it's prudent to get the certificate from the producer directly, or to call the producer to confirm the one the vendor sent. Look up their number independently rather than relying only on what's printed.
  • Keep the contact name and email; you'll need them for renewals and endorsement requests.

Red flag:Producer details that don't check out, or details the producer can't confirm when you call.

On the sample:Harborline Insurance Partners, with a named contact and a certificates mailbox.

6. Insured

Field on the form: INSURED

The person or business that bought the coverage, also called the first named insured. This should be the party you're contracting with.

What to check

  • The legal name and address should match the contract exactly.
  • Watch for DBAs, parent companies or sister companies. They may be separate legal entities with separate coverage.

Red flag:If the name differs from the contract, flag it to the contract or project manager before accepting.

On the sample:Ridgeview Site Services, LLC. Compare this against the signature block on the contract.

7. Insurers affording coverage

Field on the form: INSURER(S) AFFORDING COVERAGE · INSURER A–F

Lists each insurance company behind the policies, each tagged with a letter. The letters appear again in the INSR LTR column so you can tell which company wrote which policy.

What to check

  • Look up each insurer's A.M. Best rating. A common minimum is A- with a Financial Size Category of VII or higher.
  • Make sure every letter used in the coverage section is listed here.

On the sample:Four insurers, A through D, each writing a different line of coverage.

8. NAIC number

Field on the form: NAIC #

A five-digit ID that the National Association of Insurance Commissioners assigns to each underwriting company.

What to check

  • Use it to tell apart insurers with similar names or to look up complaint history.
  • It's helpful but not essential; a blank NAIC number on its own isn't a reason to reject.

CoverageFields 9–16

9. Coverage statement

Field on the form: COVERAGES · LIMITS SHOWN MAY HAVE BEEN REDUCED BY PAID CLAIMS

Confirms the listed policies were issued to the insured for the stated period, but adds that all policy terms and exclusions still apply and that the limits shown may already be partly used up by paid claims.

What to check

  • The certificate can't tell you how much limit remains. If that matters, ask for a current loss run for the policy period.
  • For high-risk work, require a per-project aggregate in the contract, or reserve the right to request a certified copy of the policy.

10. Certificate and revision number

Field on the form: CERTIFICATE NUMBER · REVISION NUMBER

Reference numbers assigned by the producer. The revision number goes up each time the certificate is reissued.

What to check

  • Record them in your files so you can reference the exact version when you call the producer.
  • If you receive an updated certificate, the revision number tells you which one is newest.

11. Coverage table columns

Field on the form: INSR LTR · ADDL INSD · SUBR WVD · POLICY NUMBER · EFF · EXP · LIMITS

The column headers for every coverage line. Read each row across: which insurer, whether you're an additional insured, whether subrogation is waived, the policy number, the policy period and the limits.

What to check

  • Every required coverage has an insurer letter.
  • An X appears under ADDL INSD and SUBR WVD wherever the contract requires them. Then get the endorsements.
  • Every policy number is filled in. Insist on it.
  • If a policy number reads BINDER or TBA, coverage was bound but the policy hasn't been issued yet. Accept it for now, but request a certificate showing the issued policy number within 30 days.
  • The policy period covers the whole contract. If a policy expires first, set a reminder 30 days out and request the renewal certificate.

Red flag:A binder is temporary and expires after a set number of days. If the insured never pays the premium or signs the application, the policy is never issued, even though the binder appeared on a certificate.

12. Commercial general liability

Field on the form: COMMERCIAL GENERAL LIABILITY

Covers claims from third parties for bodily injury and property damage arising from the insured's premises, operations, products and completed work. It appears on almost every certificate.

What to check

  • Occurrence form is preferred over claims-made. Occurrence covers incidents during the policy period no matter when the claim is filed.
  • Aggregate applying per Project or Location is more favorable than per Policy, because other jobs can't use up your limit.
  • Each occurrence: commonly $1M–$2M. General aggregate: often at least twice the occurrence limit.
  • Products–completed operations: for construction, contracts often require this coverage to continue 1–3 years after the job ends.
  • Med exp (often $1k–$10k) pays small injury claims without anyone proving fault.

On the sample:Occurrence form, per-project aggregate, $1M per occurrence / $2M aggregate. A solid standard GL setup.

13. Automobile liability

Field on the form: AUTOMOBILE LIABILITY

Covers injury and damage to others caused by vehicles the insured uses. The checkboxes show which vehicles are covered, and they match symbols on the auto policy.

What to check

  • Any Auto (symbol 1) is the broadest and covers any vehicle used for the business.
  • Owned (2), Scheduled (7), Hired (8) and Non-owned (9) are narrower. If one of these is checked, confirm it covers the vehicles that will be used on your job.
  • A combined single limit (often $1M) is simpler to evaluate than split per-person and per-accident limits.
  • Additional insured status is usually not needed on auto; auto policies generally extend coverage to anyone liable for the insured's conduct.

On the sample:Any Auto with a $1M combined single limit.

14. Umbrella / excess liability

Field on the form: UMBRELLA LIAB · EXCESS LIAB

Extra limits that sit on top of the underlying policies. Umbrella usually sits over general liability, auto and employers' liability. Excess often sits over general liability only.

What to check

  • Add the umbrella to the underlying limit to reach the contract total. Example: $1M GL + $4M umbrella = $5M.
  • Check for occurrence vs claims-made, the same as for GL.
  • A deductible or retention means the insured pays that amount first; note it if your contract limits self-insurance.
  • Confirm the schedule of underlying insurance. The umbrella only adds limits over the policies it lists, so verify that the GL, auto, employers' liability or professional policies you rely on are actually scheduled under it.

Red flag:An umbrella that doesn't schedule a required policy adds no limit on top of it, even if both appear on the certificate.

On the sample:$5M umbrella over $1M GL and $1M auto, for $6M total per occurrence on each.

15. Workers' compensation and employers' liability

Field on the form: WORKERS COMPENSATION AND EMPLOYERS' LIABILITY

Workers' compensation pays the insured's employees for work injuries as required by state law. Employers' liability covers related lawsuits, including claims that end up pointed at you.

What to check

  • The PER STATUTE box should be checked. If OTHER is checked, review it against the contract.
  • Employers' liability limits commonly run $500K or $1M for each of the three lines.
  • If the owner, partners or officers are excluded (Y) and they'll work on your job, their injuries could become your problem. Ask about it.
  • Waiver of subrogation on WC is common in contracts; check SUBR WVD.
  • Additional insured status isn't available on a standard workers' compensation policy. WC covers the employer's legal obligations to its own employees, so don't require AI on this line.
  • Don't mistake an alternate employer endorsement for additional insured status. It extends the employer's WC to a named alternate employer (common with staffing arrangements) and doesn't make you an additional insured.

Red flag:No workers' comp listed for a business with employees. Ask why, and get proof of a state exemption if one applies.

On the sample:Statutory WC, $1M/$1M/$1M employers' liability, no officers excluded. ADDL INSD shows N/A, which is correct for WC.

16. Other coverage

Field on the form: (OPEN LINE)

A spare line for specialty coverage, such as professional liability for architects and engineers, pollution liability for site work, liquor liability for events, or cyber.

What to check

  • Check whether the contract calls for any specialty coverage given the nature of the work.
  • Professional liability is usually claims-made. That's normal for that line, but look at the retroactive date.

On the sample:Contractors pollution liability, which makes sense for grading and earthwork.

DetailsFields 17–20

17. Description of operations

Field on the form: DESCRIPTION OF OPERATIONS / LOCATIONS / VEHICLES

Free-text remarks tying the certificate to your job: contract number, location, event, and often additional insured or waiver language. ACORD 101 can be attached if more space is needed.

What to check

  • Confirm it references your project, location or contract number.
  • Read the additional insured wording carefully. Does it name the right entities (for example officials, employees and volunteers)?

Red flag:Additional insured wording here does not create coverage. You still need the endorsement.

On the sample:Names the contract, project and the Town with its officials, employees and volunteers.

18. Certificate holder

Field on the form: CERTIFICATE HOLDER

Who the certificate was issued to. That should be your organization.

What to check

  • It should show your full legal entity name and address, not a department or a person.
  • It must match the name you're asking to be added as additional insured.

On the sample:Issued to the Town of Fairhaven, the contracting entity.

19. Cancellation

Field on the form: CANCELLATION

Current ACORD wording only promises notice "in accordance with the policy provisions." Insurers generally don't commit to notify certificate holders, and a policy can be cancelled for non-payment on as little as 10 days' notice.

What to check

  • Don't count on being told if coverage lapses. Track expiration dates yourself.
  • If you need advance notice of cancellation, require it in the contract and in the endorsement.

20. Authorized representative

Field on the form: AUTHORIZED REPRESENTATIVE

The signature of the producer or insurer representative authorized to issue the certificate.

What to check

  • The certificate should be signed, by hand or electronically.
  • The signer should line up with the producer listed in field 5.

Red flag:An unsigned certificate isn't complete. Send it back.

On the sample:Signed by D. Whitfield, the contact listed under Producer.

What a certificate can and can't tell you

A COI is a snapshot prepared by the insured's broker. It is useful evidence that coverage was bought, but the policy itself controls. Treat the certificate as the start of your review, not the end.

It shows you

  • Which insurance companies wrote each policy
  • The types of coverage purchased
  • The limits on each policy
  • Policy numbers and effective and expiration dates
  • Whether the broker indicates additional insured status or a waiver of subrogation

It doesn't tell you

  • Whether the policy is actually endorsed to add you as an additional insured
  • Whether paid claims have already reduced the aggregate limits
  • The size of any deductible or self-insured retention
  • Whether the policy has been cancelled since the certificate was issued
  • The financial strength of each insurer (check the A.M. Best rating separately)
  • Which underlying policies an umbrella or excess policy actually covers
  • The exclusions and conditions in the policy wording

Review checklist

Have the insurance section of your contract open, then work through every certificate with this list. Select View on any line to jump to that field on the sample.

Header
  • View
  • View
  • View
  • View
Parties
  • View
  • View
  • View
  • View
Coverage
  • View
  • View
  • View
  • View
  • View
  • View
  • View
  • View
Details
  • View
  • View
  • View
  • View

Six red flags to escalate

If you see any of these, pause and ask the producer or your contract manager before work starts.

  1. Producer details don't check out

    If the agent or broker listed can't be reached, or can't confirm what the certificate shows, treat the certificate as unverified until they do.

  2. Name doesn't match the contract

    A DBA, parent company or affiliate in the Insured box may mean the contracting entity isn't covered.

  3. Blank, "Binder" or "TBA" policy numbers

    Every listed policy should have an issued policy number and a full policy period. For a binder, request the issued-policy certificate within 30 days. Binders expire, and a policy the insured never pays for is never issued.

  4. Policy expires mid-contract

    Set a reminder 30 days before expiration and request the renewal certificate. Work may need to pause without it.

  5. "Additional insured" only in the description

    Wording in the remarks box does not create coverage. Ask for the actual additional insured endorsement.

  6. Old or missing issue date

    A stale date can mean a recycled certificate for a policy that has since lapsed or been cancelled.

Ask an Insurance Expert: How do I verify insurance?

Video · 9 min

Checking dozens or thousands of certificates?

Evident reads every field on every COI, compares it with your requirements and flags the gaps.

Book a Demo

FAQs

How do you read an ACORD 25?

Work top to bottom: the header and its two notices, then the parties (producer, insured, insurers), then the coverage table, then the description of operations, certificate holder and signature. Read each coverage line across: insurer letter, additional insured and waiver boxes, policy number, policy dates and limits. The walkthrough above covers every box.

How do I verify insurance on an ACORD 25?

Compare the certificate with your contract's insurance requirements. Check the insured's legal name, each required coverage and limit, policy dates that cover the work, and additional insured and waiver of subrogation status where the contract calls for them. Ask for the endorsements themselves, and call the producer on the form to confirm anything that looks off.

What is an ACORD 25?

The ACORD 25 Certificate of Liability Insurance is the standard one-page form agents and brokers use to summarize a business's liability coverage: insurers, policy numbers, coverage types, limits and policy dates. It shows the coverage in place when it was issued. It doesn't change or add to the policy.

Is an ACORD 25 proof of insurance?

It's evidence, not proof. The form says it's issued as a matter of information only and gives the certificate holder no rights. A policy can be cancelled after the certificate is issued, and additional insured status depends on a policy endorsement, not on the certificate.

How do I get an ACORD 25?

Ask your insurance agent or broker. They issue ACORD 25 certificates on behalf of your insurers, usually quickly, and need the requesting party's name and address plus any wording the request specifies. ACORD forms are licensed, so agents produce them through their own systems.

What is the latest version of the ACORD 25?

The edition in common use is ACORD 25 (2016/03). Older editions are generally still accepted, since brokers don't always switch right away. If your contract specifies an edition, follow it.